
Key Takeaways
- Everyday routines like grocery shopping and paying bills are practical money lessons in disguise.
- Children absorb financial habits best through doing, not through formal instruction.
- Age-appropriate responsibility with real money builds confidence alongside knowledge.
- Giving kids a say in small spending decisions teaches trade-offs without real financial risk.
- Connecting money concepts to things kids already care about makes the lessons stick.
Why money conversations at home matter more than formal lessons
Schools cover a lot, but personal finance gets inconsistent treatment across US curricula. A 2023 review by the Council for Economic Education found that fewer than half of states require a standalone personal finance course for high school graduation. That gap falls on families to fill, and most parents do not need a curriculum to do it. They just need to let their children watch and participate in the financial decisions already happening at home.
Children pick up money attitudes early, and much of what they absorb comes from observation rather than instruction. The habits, anxieties, and reasoning patterns that adults bring to spending and saving are visible to kids who are paying attention. Making that usually invisible process visible, and giving children small, real ways to practice, is what actually builds financial literacy.
The strategies below work across a range of ages and income levels. None of them require buying special products or setting aside dedicated teaching time. Most fit inside routines your household already has. For families also working through the broader picture, understanding how a family budget holds together gives useful context on where household money actually goes.
Age shapes what works
Children under six generally understand money as a physical object rather than a system. Concepts like saving for the future or comparing value land better around ages seven to ten, when abstract thinking develops. Teenagers can handle conversations about income, taxes, and budgeting in more direct terms. Match the complexity of the conversation to where your child actually is, not where you wish they were.
Let kids see real transactions
Most children grow up watching adults tap a card or phone and walk away with goods. Without context, money looks like magic. Narrating what you are doing at the checkout, explaining that the card pulls from money already earned, or showing a bank balance before and after a purchase gives kids a concrete picture of how transactions work.
This does not require a formal sit-down. A thirty-second explanation at the gas pump or grocery self-checkout is enough. Over time, repeated exposure to real numbers in real situations builds a working mental model that abstract lessons rarely achieve.
A thirty-second explanation at the checkout builds more understanding than an hour of abstract instruction.
Use a three-jar system for any money they receive
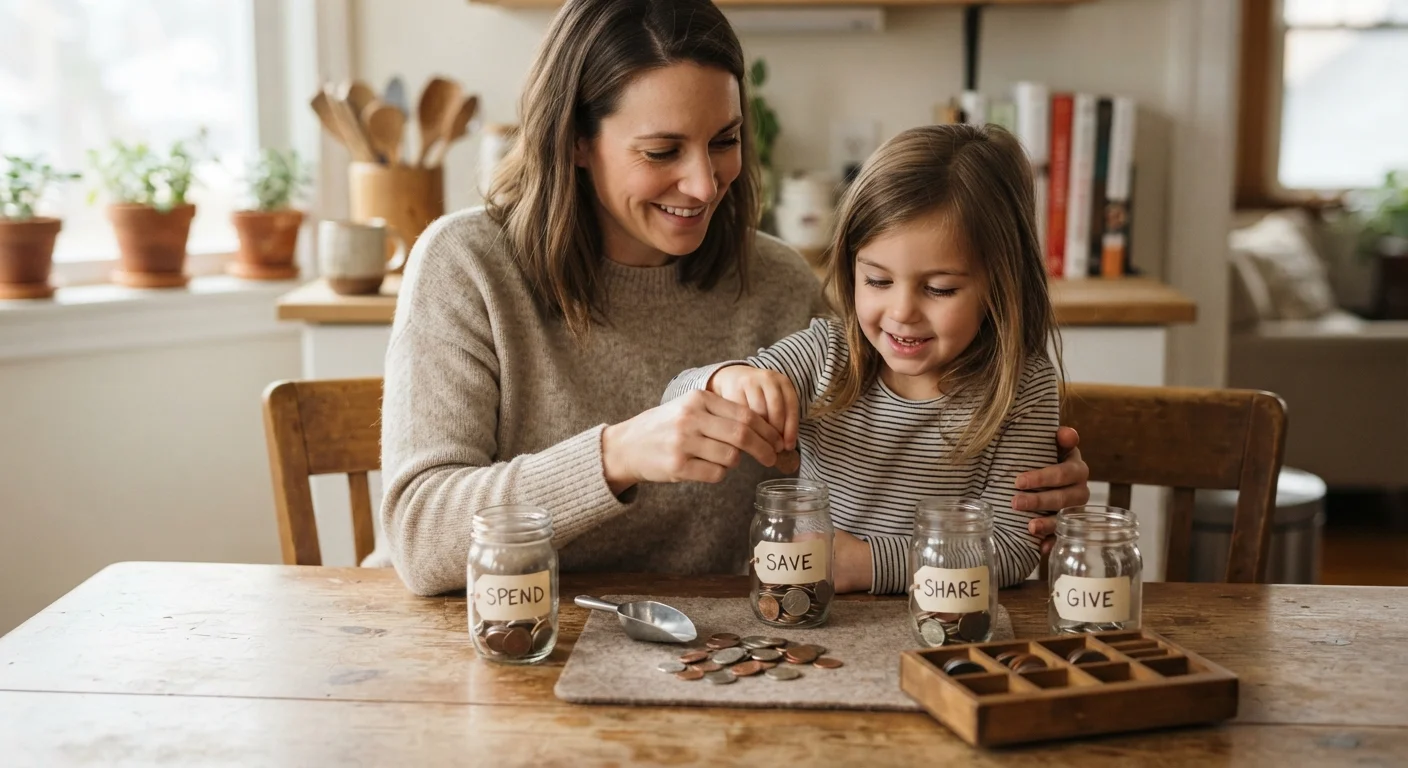
When children receive money, whether from chores, birthdays, or small tasks for neighbors, splitting it immediately into three physical jars (spend, save, give) makes the concept of allocation tangible. Labeled jars on a shelf work better for young children than app-based systems because they can see the money accumulate and deplete.
The proportions matter less than the habit. A child who puts even a small amount into a save jar every time they receive money is practicing delayed gratification, which research in behavioral economics consistently links to better long-term financial outcomes. Keep the categories fixed but let kids decide the split.
Physical jars beat apps for young children because the money is visible and real.
Involve kids in one real household spending decision per month
Pick a low-stakes, recurring expense and bring your child into the decision. Choosing between two phone plan options, comparing the cost of eating out versus cooking a family meal, or deciding whether to buy a streaming subscription for the year or month by month all work well. The goal is not to burden children with financial anxiety but to show them that adults weigh options constantly.
When kids are part of the reasoning process, they learn that money involves trade-offs, not just totals. A child who watches a parent choose the store brand cereal because it frees up money for a family activity understands something no worksheet can teach.
Watching a parent reason through a trade-off teaches more than any worksheet.
Tie earning to effort, not just existence
There is a reasonable debate among family finance researchers about whether children should be paid for basic household chores at all. A practical middle ground: separate baseline responsibilities (tidying their room, clearing the table) from optional paid tasks that are genuinely extra (washing the car, raking leaves, organizing a storage space). Baseline chores are part of being in a household. Extra tasks are a way to earn.
This distinction matters because it mirrors how employment works. Adults are not paid for making their beds; they are paid for producing something beyond their own basic maintenance. Children who experience that connection early tend to have a more grounded sense of what wages represent.
Extra tasks mirror real employment; baseline chores are simply part of household life.
Let kids make low-cost mistakes with their own money
When a child spends their entire spend jar on a cheap toy that breaks in a week, resist the impulse to replace it or to say "I told you so." The disappointment is the lesson. Buying something impulsively and regretting it is a financial experience that most adults have had too, usually at much higher cost.
The goal is not to protect children from all bad spending decisions. It is to let them encounter the consequences of those decisions while the stakes are low, in a household where they are supported. A child who learns at age nine that impulse buys often disappoint is better prepared than one who learns the same thing at twenty-five with a credit card.
A bad purchase at nine, when stakes are low, is worth more than the same lesson at twenty-five.
Connect saving to something the child actually wants
Abstract saving goals rarely hold a child's attention. Concrete ones do. If a child wants a specific item, help them calculate how many weeks of saving it will take at their current rate. Write the goal and the timeline on a piece of paper and stick it near the save jar. Check progress together weekly.
This exercise quietly introduces several real financial concepts: goal-setting, rate of savings, time value of waiting, and the satisfaction of reaching a target through accumulation. The item itself does not matter. The process is what carries over into adult financial behavior.
A written savings goal near the jar makes the concept of accumulation concrete and trackable.
Use the grocery store as a classroom
Grocery shopping with children can feel chaotic, but it is one of the richest financial environments a family has access to. Unit pricing, comparing package sizes, understanding why some items are on sale and what that actually means for the household budget, and the difference between a want and a need all show up in a single aisle.
Giving an older child a small budget to choose snacks for the week, or asking them to find the better value between two similar products, turns a routine errand into applied financial thinking. The family budget framework that keeps grocery spending in check works better when kids understand why choices at the shelf matter.
One grocery aisle contains more real financial concepts than most classroom curricula.
Putting it into practice without pressure
None of these strategies require perfection, and not every conversation will land. Some weeks the grocery budget will go over, some months the save jar will stay flat, and some purchases will be regretted. That is normal household life, and children benefit from seeing that too.
What matters is consistency over time: a household where money is talked about plainly, where children have some agency over small amounts, and where earning, spending, and saving are connected to real outcomes rather than abstract rules. Families already managing everyday spending trade-offs are already modeling the kind of thinking these strategies formalize. Bringing kids into those conversations, even briefly, is usually enough.
This article is for general informational purposes only and does not constitute financial or professional advice. For guidance specific to your family's circumstances, consult a qualified financial professional.