Emergency Fund Basics: What It Is, How Much You Need, and Where to Keep It
Key Takeaways
- An emergency fund covers unexpected costs without forcing a family into debt.
- Most financial guidance suggests saving three to six months of essential living expenses.
- Single-income households and those with variable pay often benefit from a larger cushion.
- A high-yield savings account at an FDIC-insured bank is a common place to keep these funds.
- The fund should be separate from everyday checking to reduce the temptation to spend it.
Emergency fund
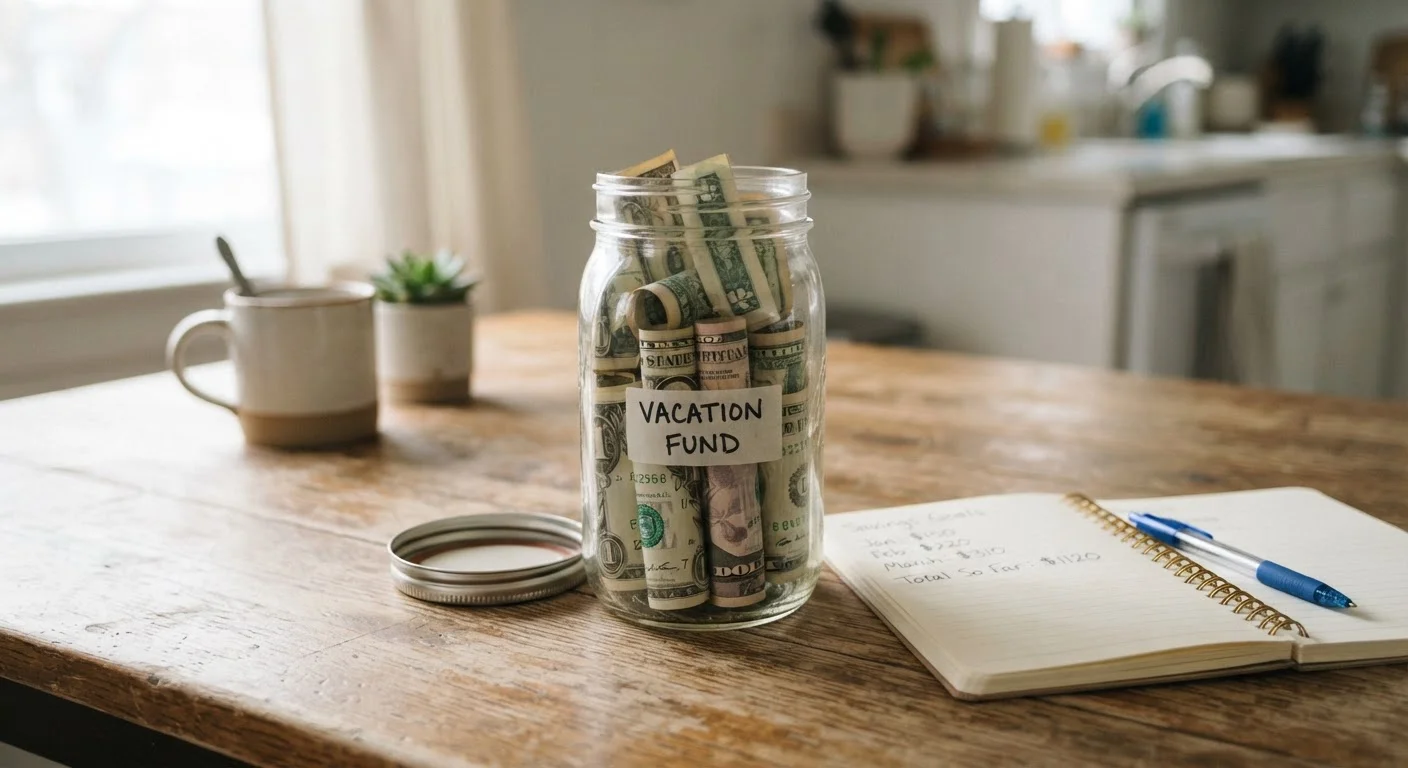
An emergency fund is a dedicated pool of savings held separately from regular spending money, reserved only for genuine financial emergencies such as a job loss, medical bill, or major car repair. It acts as a buffer that lets a household cover urgent costs without going into debt. The money stays liquid, meaning it can be accessed quickly when needed.
In personal finance, an emergency fund is distinct from both a checking account and investment accounts. It is not intended to grow wealth; it is intended to remain stable and immediately accessible.
What an emergency fund actually does
When an unexpected cost hits, a household has a limited number of options: use savings, use a credit card, borrow from family, or skip the expense entirely. Each of those alternatives except savings carries a cost, a risk, or both. A credit card charge grows with interest if it is not paid off quickly. Borrowing from family can strain relationships. Skipping a car repair or medical follow-up often makes the underlying problem worse and more expensive.
An emergency fund removes those trade-offs. The money is already there, already yours, and already designated for this purpose. A family that can cover a $1,500 car repair from savings does not need to add $1,500 to a high-interest balance or negotiate a payment plan.
The fund also has a psychological function. Knowing there is a buffer changes how a household responds to bad news. A job loss that would otherwise be a crisis becomes a problem with a defined window to solve it.
How to size your emergency fund
The three-to-six-month guideline refers to essential monthly expenses, not total income. Start by adding up the costs that absolutely must be paid every month: housing, utilities, food, insurance premiums, transportation, and minimum debt payments. That total is your monthly baseline. Multiply it by three for the minimum target and by six for the standard upper target.
Several factors push a household toward the higher end. A single-income family has no income redundancy if the earner loses a job. Self-employed workers and those paid on commission can see income drop sharply without any formal layoff. Households with a family member who has ongoing medical costs, or who works in a sector with frequent layoffs, carry more income risk than a dual-income household in a stable industry.
Set up a separate, labeled account
Naming your savings account 'Emergency Fund' at your bank is a small step that makes a real difference. When the account has a clear label and sits apart from your checking balance, it is less likely to be used for non-emergencies. Many online banks let you create and name multiple savings accounts at no cost.
Once you know your monthly baseline, divide your total target by 12 or 24 to find a monthly savings contribution that gets you there within one to two years. A smaller, consistent contribution started today builds the fund faster than waiting until conditions feel ideal.
If three to six months feels unreachable right now, a starter fund of $500 to $1,000 still reduces the probability that a minor emergency turns into credit card debt. Build from there. For a structured way to fit emergency fund contributions into monthly spending, see a household budgeting framework that accounts for irregular costs.
Where to keep the money
The account that holds an emergency fund needs to meet two requirements: the money must be safe from market loss, and it must be accessible within a day or two. Beyond that, earning some interest is a reasonable secondary goal.
A dedicated savings account at an FDIC-insured institution meets the first two requirements. Keeping it separate from your checking account adds a small but real friction that reduces casual spending from the fund. An online high-yield savings account has historically paid higher interest than a traditional passbook savings account, though rates fluctuate with the broader interest rate environment.
Accounts to avoid for this purpose include brokerage accounts, stock or bond funds, and certificates of deposit (CDs) with penalties for early withdrawal. A brokerage account could lose 20 to 30 percent of its value in a market downturn, which is exactly when you might need the money most. A CD penalty does not eliminate the option of accessing the funds, but it does reduce their value at the worst possible time.
Money market accounts at FDIC-insured banks are another workable option. They function similarly to high-yield savings accounts for this purpose, though the specific terms and rates vary by institution. Compare account terms before opening one, and verify FDIC insurance coverage.
It is worth knowing that an emergency fund is different from a sinking fund. A sinking fund is money set aside for an expected future cost, such as a new car or a home repair you can see coming. If you want to understand that distinction and how both tools fit into a savings plan, sinking funds explained covers the mechanics.
This article is for general informational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional regarding decisions specific to your household situation.