Key Takeaways
- Most family budgets break down because they ignore irregular and seasonal expenses.
- Use three to six months of actual bank statements to set realistic spending baselines.
- Sinking funds spread large, predictable costs across twelve monthly contributions.
- Children's activities need a firm annual cap before enrollment, not after.
- A short monthly review catches overspending before it becomes a debt problem.
- General financial information here is not personalized advice; consult a licensed professional for your situation.
Start here
Why most family budgets fall apart
Next
Building your income baseline
Then
Mapping fixed, variable, and irregular expenses
Apply it
Handling kids' activities and shifting costs
Make it stick
Keeping the budget working month to month
Why most family budgets fall apart
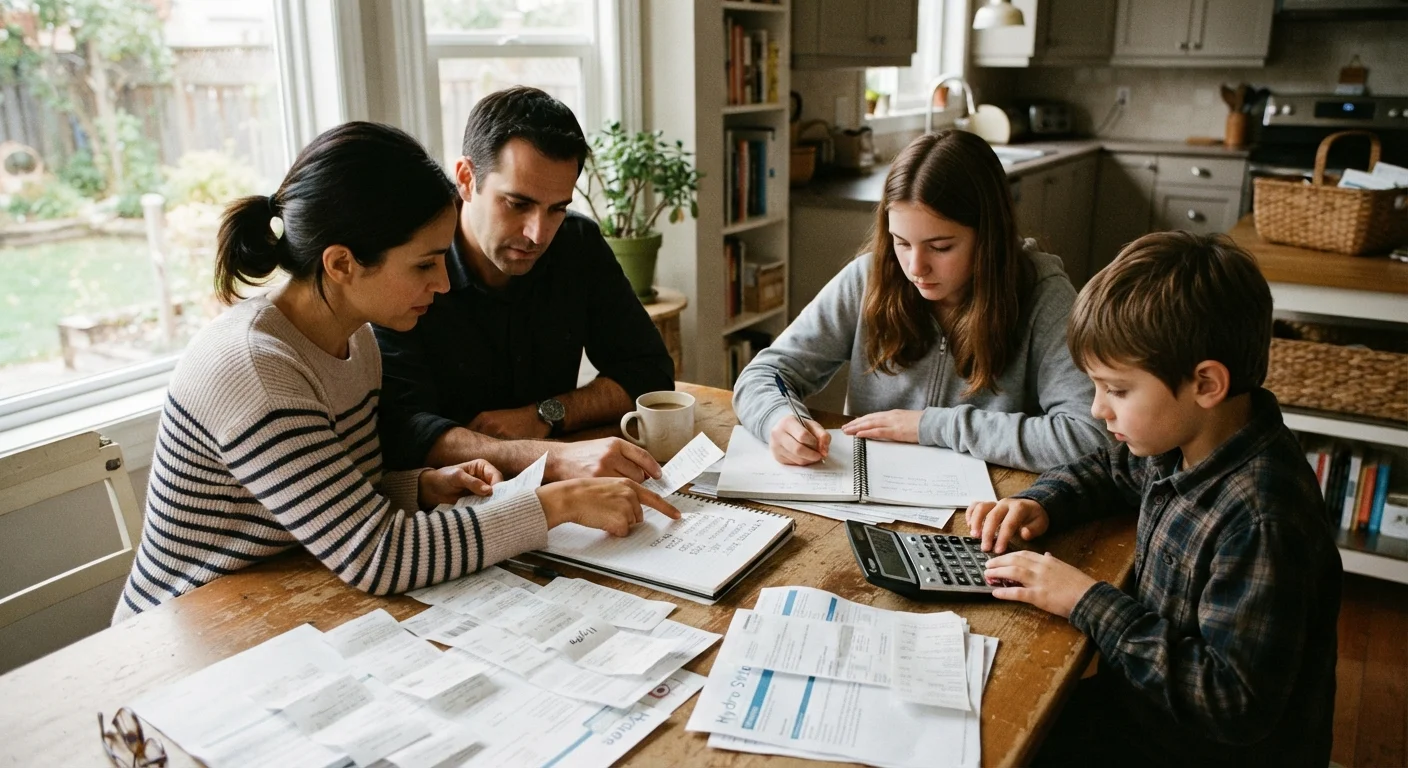
The typical household budget fails for a structural reason, not a discipline problem. Families build a spending plan around the bills they see every month and forget the costs that arrive on a schedule they do not track: the back-to-school rush, the car inspection, the dentist visit without insurance coverage, the holiday travel.
When one of those costs lands, it gets paid with whatever is in checking, which means a different category goes short. That shortfall either rolls into the next month or gets put on a credit card. Over time, the budget becomes a record of what happened rather than a plan for what comes next.
The fix is not more willpower. The fix is a budget structure that accounts for the full calendar of a family's actual life, including the irregular and the inconvenient. Understanding how a functional family budget is structured helps you see what categories matter most and where the common gaps appear.
Building your income baseline
Before allocating a dollar, you need an accurate picture of what comes in. For salaried households, that means using take-home pay after taxes and benefits, not gross income. For households with variable income from freelance work, hourly wages, or commissions, use the average of the three lowest months from the past year as your planning number. That conservative floor keeps you solvent when income dips.
If your household has two earners, budget from the combined take-home total but note what the budget looks like on one income alone. That single-income scenario is worth knowing. Families who have thought through the single-income scenario are better prepared for a job change, a parental leave, or a medical disruption.
Take-home pay
The amount deposited into your account after taxes, health insurance premiums, and any other payroll deductions are removed. This is the number a budget should be built around, not the gross salary figure.
Sinking fund
A savings pool set aside for a specific future expense you already know is coming, such as car registration or holiday gifts. You save a fixed amount each month so the cost does not disrupt your cash flow when it arrives.
Variable expense
A cost that recurs regularly but changes in amount each cycle, such as groceries or utility bills. These require a budget range rather than a fixed number.
Irregular expense
A cost that does not appear every month but is entirely predictable, such as an annual insurance premium or a school registration fee. These are the most common cause of budget shortfalls in family households.
Income floor
The lowest reliable monthly income figure a household uses as its budget baseline. For variable earners, planning from a conservative low point prevents overspending during slow months.
Mapping fixed, variable, and irregular expenses
Pull three to six months of bank and credit card statements. Sort every transaction into three buckets:
- Fixed: amounts that do not change month to month, such as rent or mortgage, car payments, and insurance premiums.
- Variable: costs that recur but shift in size, such as groceries, utilities, and fuel.
- Irregular: costs that arrive infrequently but are entirely predictable, such as annual subscriptions, vehicle registration, and school fees.
Most families handle fixed and variable expenses reasonably well. Irregular expenses cause the damage. To neutralize them, build a sinking fund for each major irregular cost. Divide the total annual amount by 12 and transfer that amount to a separate savings account each month. Sinking funds convert budget shocks into planned transfers and keep your monthly cash flow predictable.
While auditing your statements, look carefully at recurring charges. Streaming services, app subscriptions, and membership renewals often persist long after they stop being used. A subscription audit is a concrete first step toward recovering those dollars.
Handling kids' activities and shifting costs
Children's activities are among the most difficult budget categories to control because the costs are emotionally charged and socially visible. Sports registration, instrument lessons, camp fees, and club dues can total several thousand dollars a year for a single child.
The most effective approach is to set an annual per-child activity budget before enrollment season, not after. Total the anticipated costs for the year, compare that figure against your sinking fund capacity, and make activity decisions within that number. When a new activity comes up mid-year, something else has to come out or the budget has to absorb it consciously.
Set the cap before signing up
Agree on a total annual dollar limit for each child's activities before the enrollment window opens. Having that number written into your budget makes it easier to say no to an additional activity mid-year, and easier to explain why to your kids. Frame it as a household rule, not a personal refusal.
Food is a related pressure point. Families often find that meal planning is one of the fastest ways to recover budget slack without cutting anything that feels significant. A week-by-week meal planning approach can reduce grocery waste and bring a predictable structure to one of the largest variable categories in any household.
Keeping the budget working month to month
A budget that gets built once and never revisited stops reflecting reality within a few months. A short monthly review, 15 to 20 minutes, is what converts a budget from a document into a working tool.
At each review, check three things: which categories ran over, whether the sinking funds received their planned contributions, and whether any new irregular expense is coming up in the next 60 days. Adjust forward allocations based on what you learn. If groceries consistently run $80 over budget, either the grocery allocation is too low or there is a spending pattern worth examining.
Once a year, do a fuller review of insurance coverage, savings goals, and any major life changes that affect income or expenses. An annual financial checkup gives you a structured checklist for that deeper pass.
For families choosing between formal budgeting systems, the decision between zero-based and percentage-based frameworks comes down to how much detail the household is willing to track. Comparing zero-based budgeting to the 50/30/20 rule lays out the practical differences side by side.
This article is for general informational purposes only and does not constitute personalized financial advice. Consult a licensed financial professional for guidance specific to your household's circumstances.