Key Takeaways
- Children absorb money habits through repeated, low-stakes practice, not one-time explanations.
- Age-appropriate tasks like saving allowance or comparing grocery prices build real financial instincts.
- Giving kids a small amount of real money to manage teaches more than any hypothetical scenario.
- Framing spending decisions as trade-offs, not restrictions, reduces conflict and builds reasoning skills.
- Family budget conversations, kept simple and honest, normalize financial awareness without causing anxiety.
What you will need
Why most money talks miss the mark
Most families approach money education as a single conversation, triggered by a child demanding an expensive toy or asking why they cannot have something. That moment rarely lands well. The child is frustrated, the parent is reactive, and the lesson gets lost in the emotion of the exchange.
What actually shapes a child's money habits is repeated, low-pressure exposure to real financial decisions. Watching a parent weigh a purchase, helping sort change, or choosing between two items at a store teaches more than a formal sit-down talk. The goal is to make money a normal part of household conversation, not a topic that only surfaces during conflict.
For families already working to stretch every dollar, this is worth leaning into. The same budget discipline that keeps your household running is the material your kids can learn from directly. See our guide to building a functional family budget for a practical starting framework you can reference with older kids.
What to do by age group
Ages 4 to 7: Focus on the physical reality of money. Coins and bills are concrete; credit cards and apps are abstract. Give children a small transparent jar and let them watch savings accumulate. When they want something at a store, count out what they have and show them the gap between that and the price. Do not moralize; just show the math.
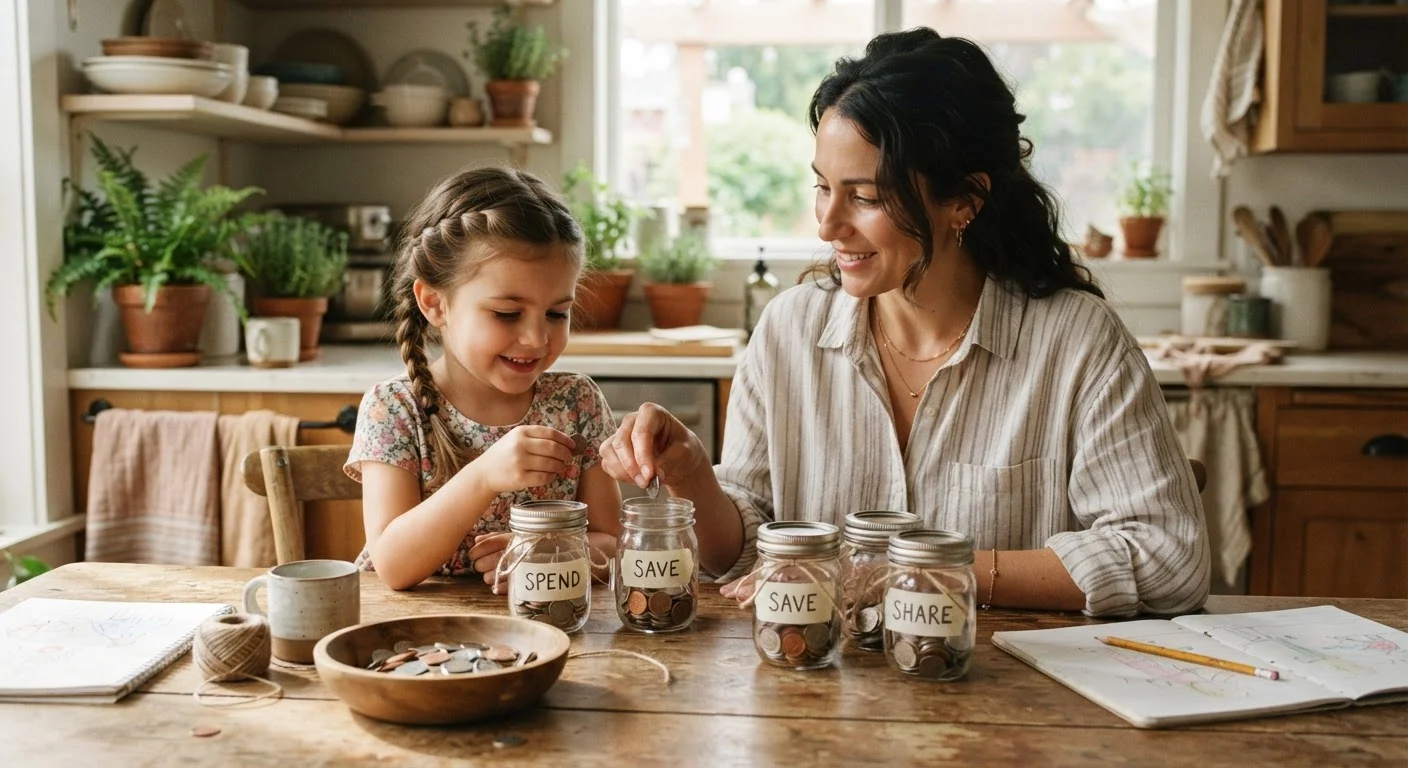
Ages 8 to 12: Introduce the three-jar method: one jar for spending, one for saving, and one for giving. When a child receives money, whether from chores, gifts, or a small allowance, they divide it themselves. The ratios are less important than the habit of dividing. At this age, kids can also start comparing prices at the grocery store. Hand them a unit-price label and ask which size is the better deal per ounce. They will remember that the next time they shop.
Ages 13 and up: Move toward a simple monthly budget for their personal expenses: clothing, entertainment, personal care. Give them a fixed amount and let them manage the trade-offs. If they spend their clothing budget in August, they manage with what they have in September. Natural consequences, without drama, are the lesson. This is also the right age to explain how a paycheck works, including what gets taken out before the money arrives.
Small amounts of real money teach more than hypotheticals
A child managing two dollars a week learns more about trade-offs than a child who completes worksheets about fictional budgets. Real money, even in tiny amounts, creates real decisions with real consequences. Start small and let the experiences accumulate over months, not a single session.
Making it practical at home
You do not need special tools or a formal curriculum. A few consistent household routines do the work.
Involve kids in real purchases. When comparing options for a large household expense, walk an older child through the reasoning. Why you might spend more upfront on something durable, or why you are choosing a store brand, are genuine financial trade-offs. These conversations give context to the choices families make. For a concrete example of how to apply this thinking to a significant purchase, the family car buying overview walks through budget-setting in detail.
Use waiting as a savings tool. When a child wants something, add it to a list and revisit it in two weeks. Many wants dissolve on their own. For those that persist, work out together how many weeks of saving it would take. A child who waits six weeks for a purchase values it differently than one who receives it the same day.
Talk about trade-offs, not restrictions. Saying "we chose not to spend money on that" rather than "we can't afford that" shifts the framing. One communicates a decision; the other communicates helplessness. Children who hear the decision framing start to apply it themselves.
For a broader look at how these habits connect to overall household financial planning, the family budget framework covers how to structure monthly spending in a way that holds up over time.
Common mistakes to avoid
Giving an allowance with no conditions is fine; giving one with no context is a missed opportunity. When you hand over money, take thirty seconds to ask what they plan to do with it. You are not approving or rejecting the answer; you are building the habit of thinking before spending.
Avoid making money a source of anxiety. Children who hear frequent, unresolved stress about finances can develop an unhealthy relationship with money long before they earn any. Keep money conversations matter-of-fact. Acknowledge when things are tight, but follow it with a specific action the family is taking, not an open-ended worry.
Do not wait until a child makes a financial mistake to have the conversation. Regular, calm exposure to everyday money decisions is more effective than a corrective lecture after something goes wrong. For more ideas on weaving financial awareness into daily routines, the Frugal Family Living hub has practical resources across all household categories.
This article is for general informational and educational purposes only and does not constitute financial advice. Consult a qualified financial professional for guidance specific to your family's situation.